Your credit card debt has hit a point where you’re googling lawyers instead of just paying the minimum. That’s a reasonable move, but attorney debt settlement isn’t automatically better than the debt settlement companies or DIY negotiation you’ve probably already looked into. A lawyer costs more upfront, sometimes a lot more, and the value depends entirely on your situation.
Here’s the direct answer: hiring an attorney makes sense when you’re facing lawsuits, wage garnishment threats, or debts large enough that a few percentage points of savings cover the legal fee. It’s usually overkill for someone with $8,000 spread across two cards who just needs breathing room. Cost typically runs as a flat fee per account or a percentage of the debt reduced, and fee structures vary widely between firms.
This article breaks down what an attorney actually does that a settlement company or nonprofit counselor doesn’t, how much you should expect to pay, red flags that signal a bad hire, and the specific debt situations where a lawyer earns their fee.
Why hiring a debt settlement attorney can pay off
An attorney brings something a debt settlement company can’t offer: legal representation that creditors and collection lawyers have to take seriously. When a law firm sends a letter on its letterhead, the creditor’s attorney knows they’re now dealing with someone who can file an answer to a lawsuit, raise defenses, and drag out litigation if needed. That changes the negotiation dynamic completely. Settlement companies can only ask nicely; a lawyer can actually respond in court.
Legal protection creditors can’t ignore
Creditors escalate faster when a lawsuit is already filed or threatened. A credit card debt lawyer can answer the summons, challenge the creditor’s standing to sue, and buy time while negotiating a lump-sum payoff. Nonprofit credit counselors and debt settlement companies generally step back once litigation starts, because they’re not licensed to represent you in court. This is the single biggest reason people search for attorney debt settlement instead of the cheaper alternatives.
A lawsuit changes everything: it’s the moment a settlement company’s help runs out and a lawyer’s job begins.
Privilege and leverage most people underestimate
Conversations with your attorney are protected by attorney-client privilege, so you can be candid about your finances without worrying it gets used against you. That same attorney can also negotiate a full and final settlement agreement with language that protects you from the creditor coming back later for the difference, something DIY negotiators often get wrong when they settle informally over the phone.
Cases where the math favors a lawyer
The fee makes the most sense in specific scenarios:
- You’ve already been served with a lawsuit or judgment threat
- Your debt exceeds $25,000 and spans multiple creditors
- A creditor is threatening wage garnishment or a bank levy
- You’re self-employed or own assets a judgment could put at risk
- You need a settlement agreement that legally protects you from future claims
In each of these, the legal fee is small compared to what’s at stake. Someone facing a $40,000 judgment risk isn’t comparing attorney costs to a debt management plan’s fee, they’re comparing it to losing a chunk of their paycheck every month for years.
How to find and hire the right debt settlement attorney
Finding a competent lawyer takes more effort than picking the first result for “debt relief attorney near me.” Start with your state bar association’s referral service, which vets licensing and lets you filter by practice area like consumer debt or creditor litigation. Avoid firms that advertise heavily on late-night TV promising to “erase your debt,” since aggressive marketing often signals a settlement mill with attorneys who barely touch your file.
Vet credentials before you sign anything
Check that the attorney is actually licensed in your state and has handled debt settlement or collection defense cases specifically, not just general practice. Ask these questions during a consultation:
- How many debt settlement negotiations have you personally handled this year?
- Will you personally negotiate, or does a paralegal handle communications?
- What’s your average settlement percentage compared to the original balance?
- Can you provide references from past clients with similar debt levels?
- What happens if a creditor sues before we settle?
Most reputable attorneys offer a free initial consultation, so use it to gauge responsiveness and clarity, not just credentials on paper.
Red flags that should end the conversation
Walk away if the attorney demands large upfront fees before doing any work, guarantees a specific settlement amount, or can’t clearly explain how they handle trust accounts for your settlement funds. Legitimate firms hold your money in a separate account until a deal closes, similar to how debt settlement companies are required to operate under FTC rules. If nobody can explain that process in plain language, keep looking. A rushed sales pitch instead of a real case assessment usually means you’re talking to a lead generator, not a practicing attorney.
What attorney debt settlement really costs
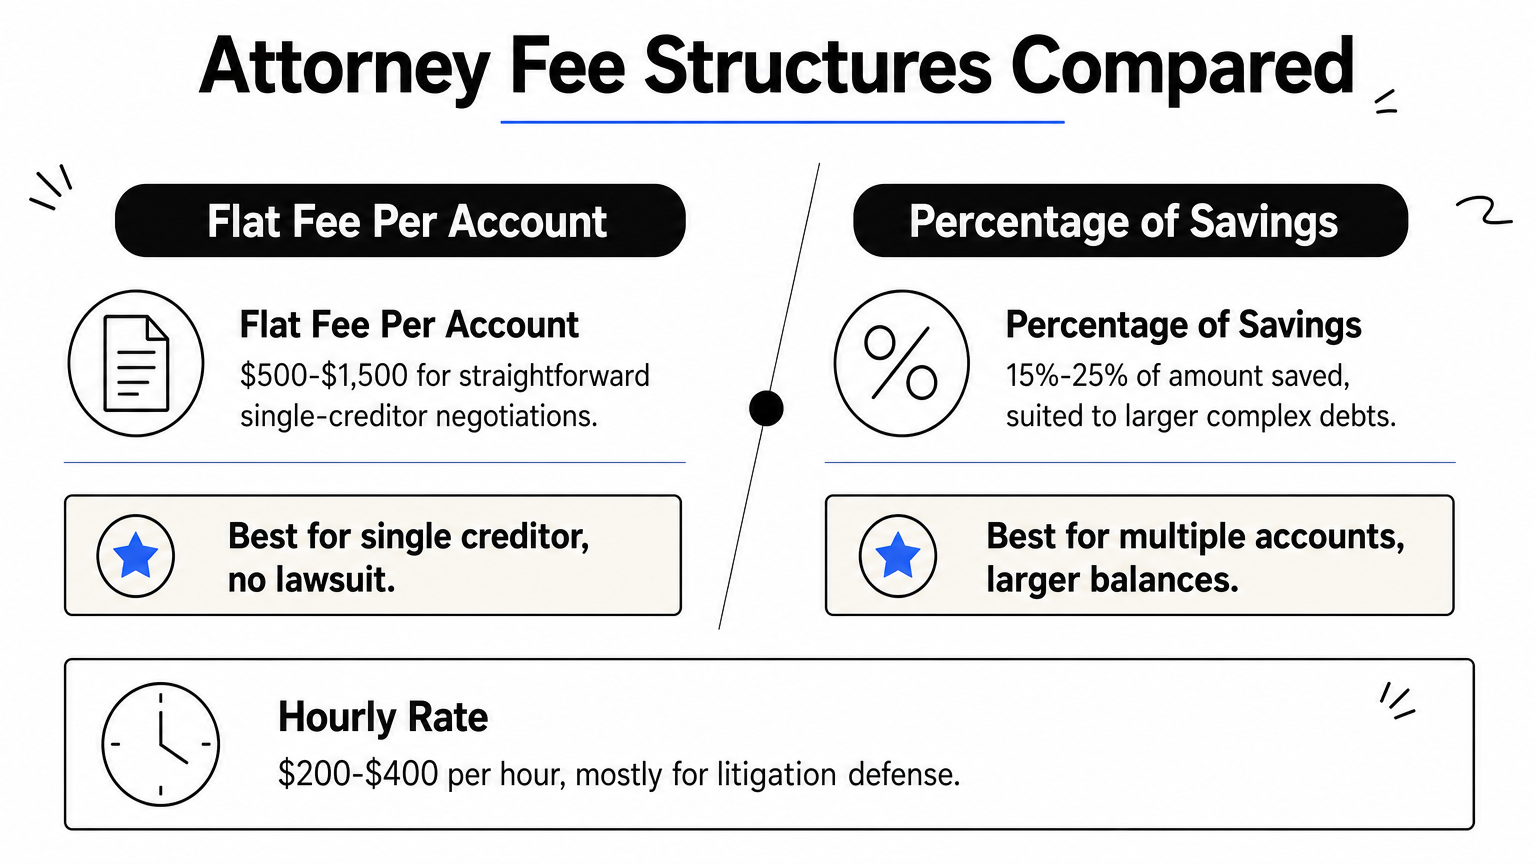
Pricing for attorney debt settlement isn’t standardized, so you’ll see three common models depending on the firm and your state. Flat fees per creditor are common for straightforward negotiations, often $500 to $1,500 per account. Percentage-based fees, usually 15% to 25% of the amount saved (not the original balance), suit larger or more complicated debts. Hourly billing, typically $200 to $400 an hour, shows up mostly in litigation defense rather than pure negotiation work.
Comparing the fee structures
| Fee Model | Typical Range | Best For |
|---|---|---|
| Flat fee per account | $500-$1,500 | Single creditor, no lawsuit |
| Percentage of savings | 15%-25% | Multiple accounts, larger balances |
| Hourly rate | $200-$400/hr | Active lawsuits, court appearances |
Quoting a wide range like this isn’t hedging, it’s reality: your final cost depends on how many creditors, how much debt, and whether litigation is already in play.
The real cost of hiring a lawyer isn’t the fee itself, it’s what happens if you skip one and get sued anyway.
What that fee should actually include
Reputable firms explain upfront whether the fee covers ongoing creditor communication, drafting the final settlement letter, and court representation if a lawsuit gets filed mid-negotiation. Some firms charge separately for litigation defense on top of the negotiation fee, which can catch clients off guard if it’s not spelled out in the retainer agreement. Verify this in writing before signing, since a vague retainer is often the first sign of a firm that nickel-and-dimes clients once the case gets complicated.
Attorney vs. DIY negotiation vs. settlement companies
Comparing your three real options side by side makes the tradeoffs obvious fast. DIY credit card debt negotiation costs nothing but your time, works fine for one or two accounts under $5,000, and falls apart the moment a creditor’s collection attorney gets involved. Debt settlement agencies charge 15% to 25% of enrolled debt, handle multiple creditors at once, but can’t represent you if you’re sued. Attorney debt settlement costs the most upfront but is the only option that includes actual legal representation.
Side-by-side comparison
| Option | Typical Cost | Handles Lawsuits? | Best For | |—|—|—| | DIY negotiation | $0 | No | Small debt, 1-2 creditors | | Settlement company | 15%-25% of enrolled debt | No | Multiple accounts, no active lawsuit | | Debt settlement attorney | $500-$1,500/account or 15%-25% of savings | Yes | Lawsuits, judgments, large balances |
If a creditor can sue you and win, only one of these three options can stand up in that courtroom.
Why the choice isn’t really about price
Price matters less than what happens when negotiations stall. A settlement company will tell you to keep saving toward a lump sum while a creditor sues you anyway, and once that happens, you’re on your own for legal defense. Someone juggling straightforward, smaller balances rarely needs to pay attorney rates and can get results by haggling with creditors directly. Larger debts, active lawsuits, or judgment risk change that math completely, and paying more upfront for representation often costs less than losing a lawsuit later.
Deciding what’s right for your debt
Attorney debt settlement isn’t the default answer, it’s the answer for specific situations: lawsuits, judgment risk, or debt loads big enough that legal fees are a rounding error against what you’d lose otherwise. If you’re facing a summons or a creditor threatening garnishment, stop shopping for the cheapest option and start shopping for licensed representation. If your debt is modest and no lawsuit is on the table, a settlement company or even DIY negotiation probably saves you money without sacrificing much protection.
The honest test is simple: would losing this fight in court cost you more than the legal fee? If yes, hire the lawyer. If no, save your cash and negotiate directly. Either way, understanding your full range of options before creditors force your hand puts you in control. Keep exploring the strategies and comparisons in our guide to finding the right credit card solution before you commit to a path.