You are retired, your income is fixed, and the credit card balance keeps growing at 24% a year. Then you search for senior debt relief programs hoping a government office will wipe it out. It is a fair hope, and it is the one most scammers count on.
Here is the direct answer. No federal program forgives credit card debt for seniors, and no government agency will pay it off because of your age. What does exist is a set of real tools you can use: nonprofit credit counseling, debt management plans, consolidation, and, as a last resort, settlement. Some work well on a fixed income. Others carry real risks, especially for people living on Social Security.
Below, we sort what is real from what is marketing. You will see how each option works, who qualifies, what it costs, and how Social Security and retirement income are protected from creditors. You will also learn the warning signs of senior debt relief scams, so you can take the next step with confidence.
Why senior debt relief programs are so confusing
Real help exists, just not for this debt
Part of the confusion is that help for seniors is real. It just targets other costs. Housing, health care, food, and utilities all have age-based or income-based support, and none of it cancels a credit card balance. Here is how the pieces line up.
| Type of help | Real for seniors? | Erases credit card debt? |
|---|---|---|
| Medicare Savings Programs | Yes, income-based | No |
| State property tax relief | Yes, varies by state | No |
| SNAP and LIHEAP | Yes, income-based | No |
| Nonprofit credit counseling | Yes, open to all ages | No, it lowers interest and sets a payoff plan |
| "Senior debt forgiveness" | No federal program | No |
Marketing borrows the language
Search ads for senior credit card debt relief often use official-sounding names, flags, and phrases like "government-approved." Many come from for-profit settlement companies. They are selling a service, not running a public program, and the word "senior" is there to get your click.
No government office forgives credit card debt because of your age, so any offer that says otherwise is a sales pitch.
Another source of confusion is the phrase "debt relief" itself. It covers very different products: nonprofit counseling, consolidation loans, settlement, and bankruptcy. Each one has different costs and different damage to your credit. An ad that lumps them together hides the tradeoffs you most need to see.
Finally, retirees get targeted because they often have steady income, good credit history, and little time for trial and error. That is why credit card debt relief for seniors is a crowded market. Knowing the real options first lets you tell help from hype.
How to get credit card debt relief as a senior
Real senior debt relief programs come down to four tools, ranked from safest to riskiest. The options for credit card debt relief for senior citizens match what anyone gets, but a fixed income changes which one fits you.
Start with nonprofit credit counseling
A nonprofit credit counseling agency reviews your budget for free, then may enroll you in a debt management plan. The agency negotiates lower interest rates, often into single digits, and you make one monthly payment for a modest fee. Most plans finish in three to five years, which suits a predictable budget. Look for agencies affiliated with the National Foundation for Credit Counseling.
Start with a nonprofit counselor, because it is the cheapest route and the least damaging to your credit.
Compare the other options
| Option | Best for | Main risk |
|---|---|---|
| Balance transfer card | Scores near 700+, balance you can repay in 12 to 21 months | 3% to 5% transfer fee, high rate after the promo |
| Consolidation loan | Fair to good credit, steady income | Denial, origination fees |
| Debt settlement | Real hardship, no other path | Credit damage, lawsuits, taxes |
Debt settlement belongs at the bottom. Companies usually tell you to stop paying first, which brings late fees and collection calls. Forgiven debt can also count as taxable income, so a settled $10,000 may produce a surprise tax form.
How to spot senior debt relief scams and risky settlement
Red flags that should end the call
Scams aimed at senior citizen credit card debt relief searches follow a pattern. For-profit companies that sell by phone cannot legally charge fees before they settle a debt, according to the FTC. Watch for these red flags:
- Upfront or "enrollment" fees
- Guaranteed results or promises to erase your balance
- Advice to stop paying and stop talking to creditors
- Pressure to decide today
- Requests for your Social Security number or bank login before explaining terms
- Claims of a "government-approved" program
If a company wants money before it settles a single debt, hang up.
Why even legitimate settlement is risky
Even honest settlement is rough on a fixed income. Companies tell you to stop paying, so late fees and interest pile up while the creditor may sue. A lawsuit can end in a judgment, and the settled account stays on your report for seven years.
Taxes add another surprise. Forgiven debt of $600 or more usually arrives as a 1099-C form, and the IRS may treat the forgiven amount as taxable income.
Ask for every fee in writing, and check your state attorney general’s complaint records before you sign anything. A real company will not mind the extra time.
What Social Security and retirement accounts protect
Before you consider any of the senior debt relief programs above, know what a credit card company cannot touch. It changes how much leverage you have.
Social Security is shielded from card collectors
Federal law bars credit card companies from garnishing Social Security benefits. Banks must also automatically protect two months of federal benefit deposits if a garnishment order hits your account. A card issuer can still sue you, call you, and win a judgment, but it generally cannot take your benefits.
Some creditors do have access:
- The IRS, for back taxes
- Federal student loan collectors
- Child support and alimony enforcement
Keep benefits in their own account, so protected money stays easy to trace and never mixes with other deposits.
Retirement accounts are less uniform
Employer plans such as a 401(k) or a pension usually fall under ERISA, which shields them from most creditors. IRAs depend more on state law, and protection can vary a lot outside bankruptcy. Check your state’s rules or ask a consumer attorney.
Many retirees make one costly mistake here. They empty an IRA to pay a card, which creates a tax bill on the withdrawal and moves safe money into a debt that could never have reached it.
Never drain protected savings to pay an unsecured card balance.
This protection also explains why some seniors with only Social Security income hold "judgment-proof" status. The debt is still owed, but collectors have little to seize.
How to choose the right option for your situation
Which of the senior debt relief programs fits you depends on three things: your credit score, your income after essentials, and how much a creditor could actually collect. Use the table below as a starting point, then test it against your own budget.
Match your situation to an option
| Your situation | Best fit |
|---|---|
| Score near 700+, can repay in 12 to 21 months | Balance transfer card |
| Fair credit, steady pension or Social Security | Consolidation loan or debt management plan |
| Damaged credit, can afford a reduced payment | Nonprofit debt management plan |
| Only protected income, little to seize | Free legal aid or a nonprofit counselor |
Notice that settlement is missing. It stays a last resort, and a monthly plan fee often costs less than a loan with origination fees.
Run a quick budget test
Start with your fixed income and your essential bills. What remains is what you can safely put toward debt.
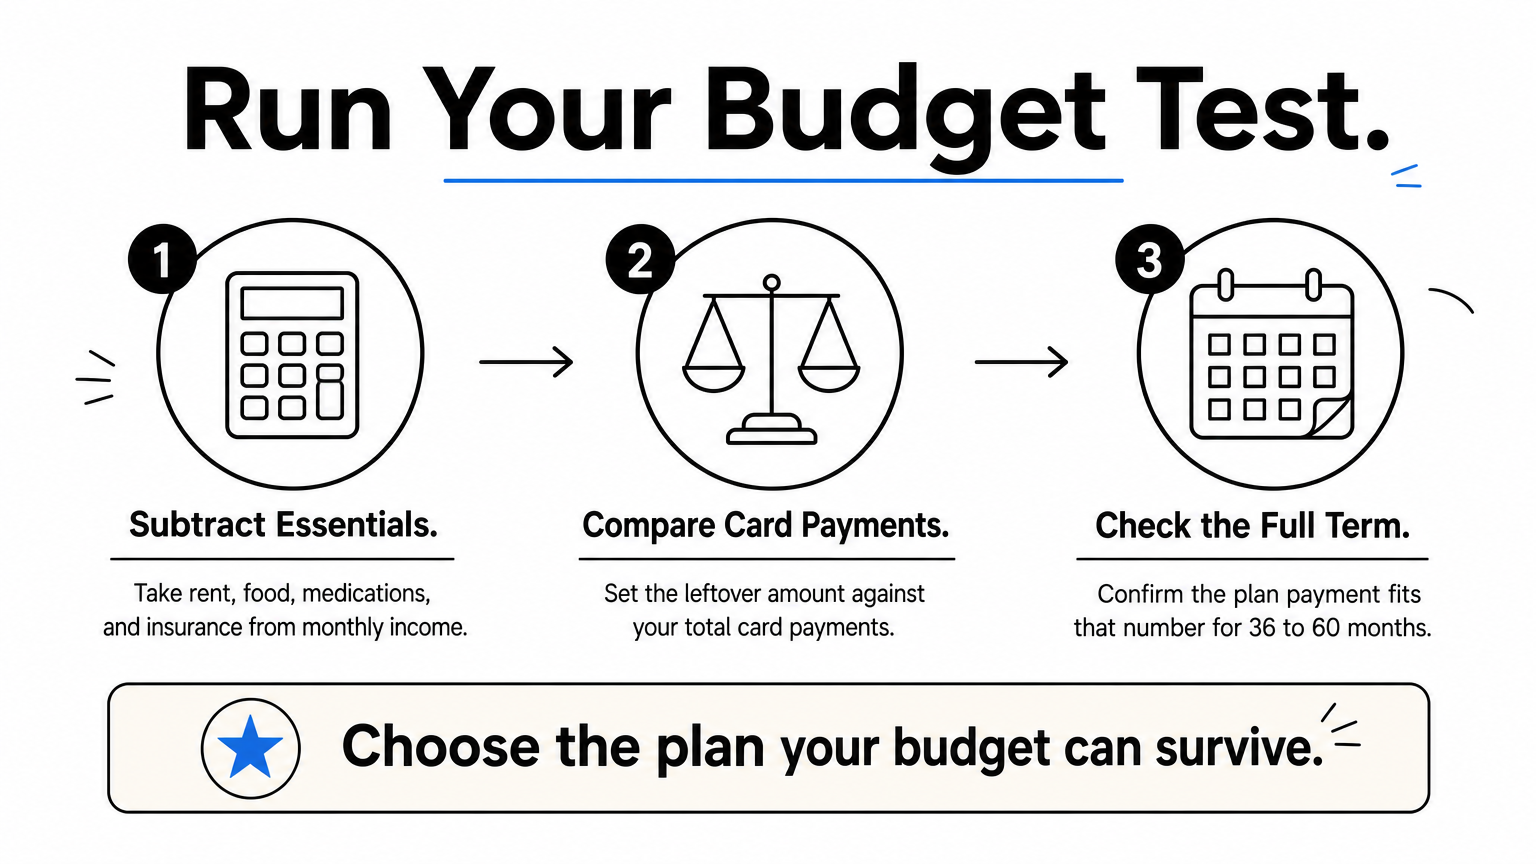
- Subtract rent, food, medications, and insurance from your monthly income.
- Compare the leftover amount to your total card payments.
- Check that any plan’s payment fits that number for its full term.
Pick a payment you can keep up for 36 to 60 months. A plan that strains your budget will collapse, and missed payments can cancel your interest breaks.
Choose the plan your budget can survive, not the one with the best headline rate.
Where to start today
The honest picture is simple. No federal program forgives credit card debt for seniors, but the real senior debt relief programs, built on nonprofit counseling, debt management plans, and consolidation, can cut your interest and give you a payoff date. Settlement stays a last resort, and any company asking for fees upfront should lose your call.
Your first step this week takes about an hour. List every card, balance, and rate. Total your fixed income and essential bills. Then book a free session with an NFCC-affiliated nonprofit counselor. Keep your Social Security in its own account, and never drain an IRA to pay a card.
Want more help? Read our free guides on debt relief programs, balance transfers, consolidation, and debt management plans. Then choose the option your budget can survive and take the first step today.