
When your credit card balances keep growing despite on-time payments, a debt relief program starts to look like a lifeline. Some are. Others cost you thousands and wreck your credit. Weighing the pros and cons of debt relief programs before you sign anything is the single best way to avoid the second kind.
Here is the short answer. No single program is best for everyone. A debt management plan usually suits people with steady income and damaged credit. Debt consolidation works best if your score is above roughly 670. Debt settlement and bankruptcy are last resorts, and both carry real costs, including credit damage lasting 7 to 10 years in many cases.
Below, you will see four options compared side by side: debt settlement, debt management plans, debt consolidation, and bankruptcy. For each one, we cover how it works, what it costs, how it affects your credit, and who it fits. Use it to narrow your choices before you call a credit counselor or any company that promises quick results.
1. Debt management plans
How it works
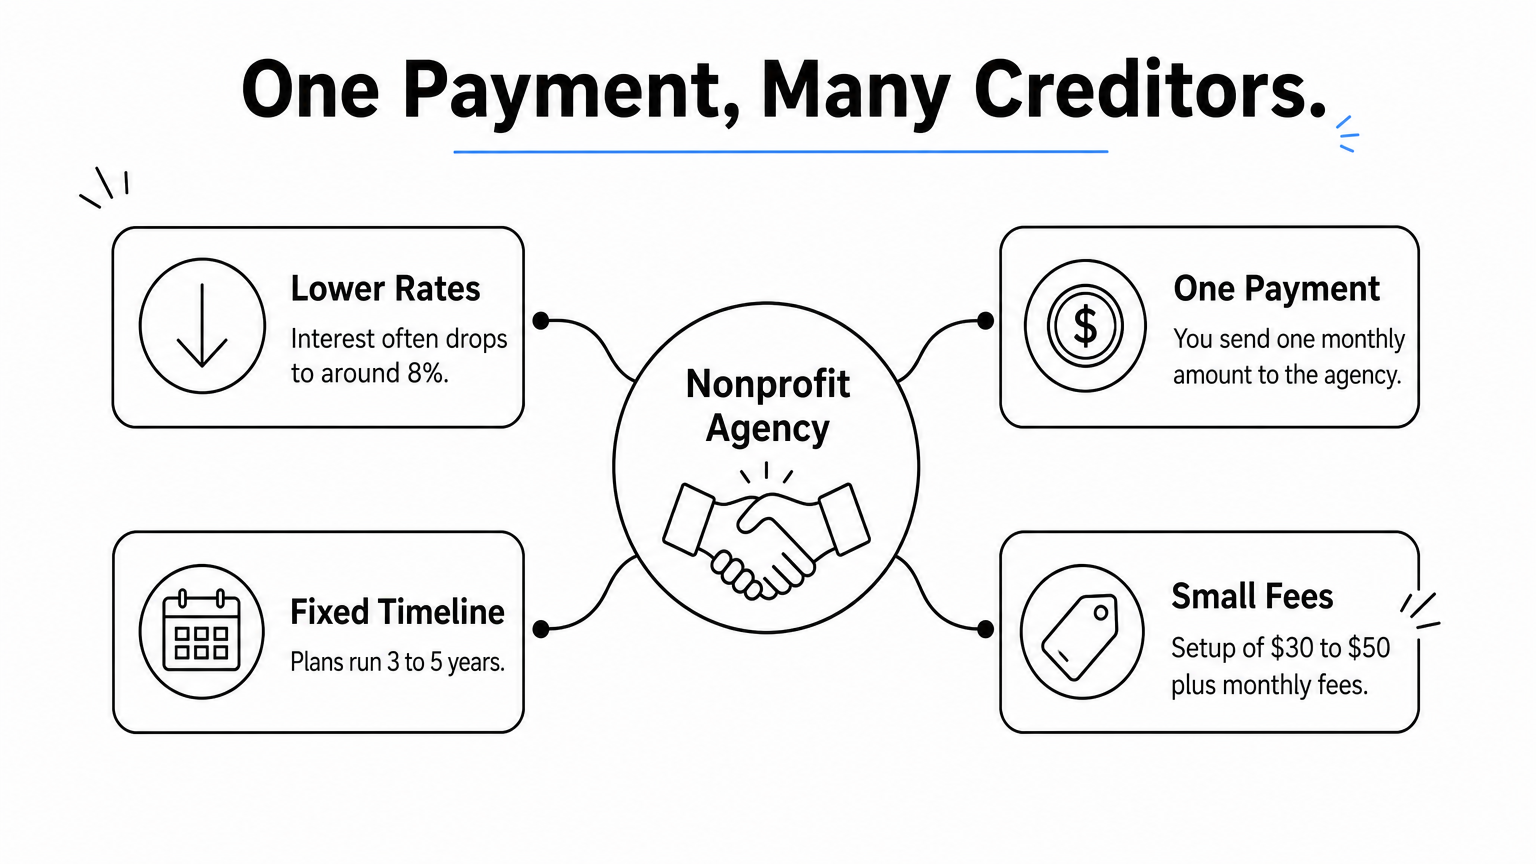
A nonprofit credit counseling agency reviews your budget, then asks your card issuers to cut your interest rates and waive late fees. You send the agency one monthly payment, and it pays your creditors. Typical terms:
- Interest rates: often reduced to around 8%
- Length: 3 to 5 years
- Fees: setup of roughly $30 to $50, plus $25 to $55 a month
Pros
Among the pros and cons of debt relief programs, a debt management plan is the lowest-risk option for most people. It repays your balances in full, so you avoid the tax and credit fallout of forgiven debt.
- Lower rates send more of each payment to principal
- One payment replaces several due dates
- No minimum credit score is required
- On-time payments can rebuild your payment history
Cons
Expect a few tradeoffs. Most agencies require you to close the enrolled cards, which can dip your score at first.
- Fees add up to hundreds of dollars over the plan
- One missed payment can cancel the plan and restore your old rates
- It covers unsecured debt like credit cards, not mortgages or car loans
- You need steady income for 3 to 5 years
Who it suits best
Think of a DMP if you carry high balances at 18% or more, earn steady income, and have a score too low for a good consolidation loan.
A debt management plan repays everything you owe, just at a lower cost and on a fixed schedule.
Skip it if your debt is too big to repay within five years. In that case, compare settlement or bankruptcy with a nonprofit counselor before you decide.
2. Debt consolidation
How it works
You take out a personal loan or a 0% balance transfer card and use it to pay off your credit cards. Then you owe one lender instead of several. Loans usually run 2 to 7 years at a fixed rate and payment. Transfer cards often give 12 to 21 months at 0%, with a 3% to 5% fee.
Pros
Consolidation cuts your interest cost if you qualify for a rate well below your card APR. It also gives you a clear payoff date.
- Funding often arrives within days
- Your cards stay open, so utilization drops
- No forgiven-debt tax bill
Cons
The catch is that good credit is required. Borrowers under 670 often see rates of 25% or more, which erases the savings. Origination fees of 1% to 10% can also eat into the loan. The biggest danger is running the cards up again.
Consolidation fixes your interest rate, not the spending habit that built the balance.
Who it suits best
Choose it if your score is 670 or higher, your income is steady, and you can repay within the term. Of the debt relief programs pros and cons covered here, consolidation is the cheapest route when you qualify. If you can’t get a rate below your current APR, move on to a debt management plan.
3. Debt settlement
How it works
A debt settlement company tells you to stop paying your cards and deposit money into a savings account instead. Once accounts are seriously delinquent, it offers creditors a lump sum worth less than you owe. Programs run 2 to 4 years. Fees run 15% to 25% of enrolled debt, and federal rules bar charging them before a settlement.
Pros
Settlement can shrink your balance by a large margin. It also works when you cannot repay in full.
- Debt can end in 2 to 4 years
- No minimum credit score
- Avoids a bankruptcy filing
Cons
Among the pros and cons of debt relief programs, settlement carries the heaviest risk. Your score drops sharply while you stop paying, and creditors can sue before a deal closes.
- Late marks stay on your report for 7 years
- Forgiven debt may count as taxable income
- Creditors can refuse to negotiate
- Fees reduce your savings
Settlement asks you to damage your credit first and hope the savings arrive later.
Who it suits best
Consider it only if you are already behind, face a real hardship, and cannot repay within five years. Otherwise, talk to a nonprofit counselor first. Many people who hear settlement pitches qualify for cheaper options.
4. Bankruptcy
How it works
You file a petition in federal court, and an automatic stay halts most collection calls and lawsuits. Chapter 7 wipes out qualifying unsecured debt in about 3 to 4 months, but you must pass a means test. Chapter 13 sets a 3 to 5 year repayment plan based on your income. Both require a credit counseling course first.
Pros
Bankruptcy is the only option here that can erase debt you truly cannot repay, and it works under court protection.
- Collections and lawsuits stop right away
- Chapter 7 can finish in months
- No negotiating with creditors
Cons
Of all the pros and cons of debt relief programs, bankruptcy does the most lasting credit damage. A filing stays on your report for 7 to 10 years, and Chapter 7 may cost you nonexempt property.
- Attorney and court fees can reach $1,500 or more
- Student loans and most tax debts usually survive
- Future loans and cards cost more
Who it suits best
Consider it if your debts exceed what you could repay in five years and settlement looks too risky. Book a consultation with a bankruptcy attorney, since many offer the first meeting free.
Bankruptcy is a legal reset, but it belongs after cheaper options have been ruled out.
How to choose the right debt relief option
Match the option to your situation
Start with two facts: your credit score and whether you can repay everything within five years. Those answers cut the pros and cons of debt relief programs down to one or two realistic choices.
| Your situation | Start with |
|---|---|
| Score 670+, steady income | Debt consolidation |
| Lower score, steady income, repayable in 5 years | Debt management plan |
| Behind on payments, cannot repay in 5 years | Settlement or bankruptcy |
| Lawsuits looming, few assets | Bankruptcy attorney consult |
Choose the cheapest option you can actually finish, not the one with the fastest promise.
Vet the provider before you sign
Next, look at who is asking for your money. Nonprofit counselors explain fees upfront and put the plan in writing. Walk away if you see:
- Fees charged before any debt is settled
- Guaranteed results or talk of "government programs"
- Advice to stop paying without a credit warning
Finally, get a free session with a nonprofit counselor before committing. It costs nothing and can confirm your pick.
Making the call that fits your debt
Every option here trades something. A debt management plan costs you time and open cards, consolidation demands good credit, settlement risks your score, and bankruptcy leaves the longest mark. The pros and cons of debt relief programs only matter once you match them to your own numbers. Your credit score and your ability to repay within five years decide most of the answer.
Start with the cheapest option you can actually finish. Talk to a nonprofit counselor, get every fee in writing, and never pay a settlement company upfront. One honest hour of comparison now can save you thousands later.
When you want to keep learning before you act, read our guide on how to get out of credit card debt at Credit Card Solution. You will find step-by-step help on balance transfers, consolidation loans, and rebuilding your score, so your next move is an informed one.


No Responses